What is the comprehensive market overview for the Gas Pipeline Infrastructure Market?
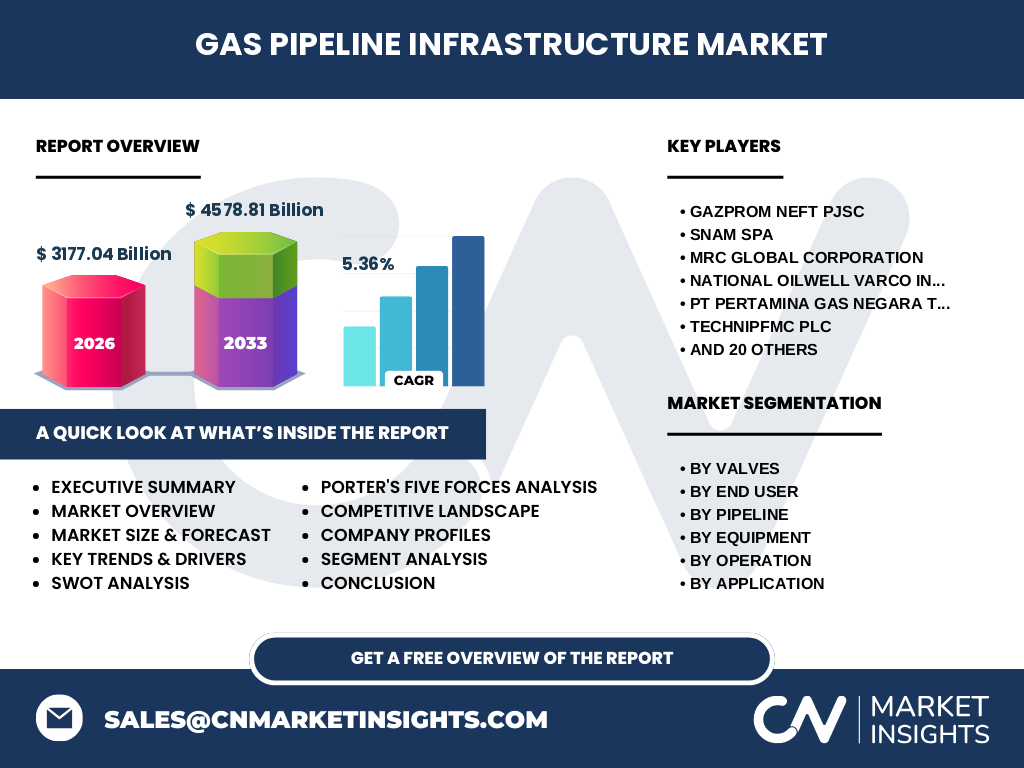
Our analysis indicates that the Gas Pipeline Infrastructure Market represents a foundational pillar of global energy logistics, valued at 3177.04 Billion in 2026. This sector encompasses the intricate network of steel and polyethylene conduits, compressor stations, and metering skids essential for transporting hydrocarbons from extraction sites to commercial and residential end-users.
Structural Growth Drivers and Market Restraints
Based on our research, primary growth drivers include rising global energy demand and massive investments by operators like Kinder Morgan Inc. and Enbridge Inc. However, the sector faces stringent environmental regulations from bodies such as FERC and localized NIMBY opposition regarding right-of-way permissions, which heavily constrain project timelines and inflate baseline capital expenditures.
Emerging Trends Shaping the Gas Pipeline Infrastructure Market
The data suggests a rapid technological pivot toward hydrogen-blend readiness and smart pipeline monitoring. Industry innovators are integrating advanced gas flow metering skids and automated ball valves to minimize fugitive methane emissions, favoring engineering giants like TechnipFMC plc that possess proprietary decarbonization capabilities.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted global supply chains for heavy raw materials like high-grade steel and coated pipeline segments. Despite initial project suspensions, active participants such as TC Energy Corporation spearheaded the post-pandemic recovery by accelerating digital asset management and remote compressor station operations to ensure uninterrupted transmission.
Competitive Benchmarking in the Gas Pipeline Infrastructure Market
Market concentration remains moderately high, characterized by strategic consolidation among capital-intensive midstream operators. Key players like Gazprom Neft PJSC, Snam SpA, and Saipem SpA leverage massive balance sheets to dominate cross-border transmission corridors, while niche equipment suppliers focus on high-precision pressure regulating metering skids.
Executive Summary: Key Findings on the Gas Pipeline Infrastructure Market
Our executive synthesis reveals that the Gas Pipeline Infrastructure Market is poised for robust expansion, driven by urbanization and energy security mandates. Strategic partnerships and digital transformation across distribution networks remain the primary catalysts for sustained operational efficiency among leading multinational energy corporations.
Market Forecast for the Gas Pipeline Infrastructure Market from 2027 to 2033
Our projections indicate that the market will surge from 2027 to 2033, reaching an impressive valuation of 4578.81 Billion by the end of the forecast period. This trajectory reflects a steady compound annual growth rate (CAGR) of 5.36%, fueled by capital injections into offshore transmission pipelines and domestic distribution upgrades.
Segmentation Analysis of the Gas Pipeline Infrastructure Market
The market segments intricately across multiple operational vectors. By equipment, it spans pipelines, valves, compressor stations, and metering skids. By pipeline material, it divides into steel, polyethylene, and coated pipelines. Operational scopes separate into transmission and distribution, while applications bifurcate into on-shore and off-shore environments serving commercial and residential sectors.
Regional Market Analysis and Geographic Distribution
Geographically, the market exhibits pronounced regional variance driven by indigenous hydrocarbon reserves and regulatory frameworks. North America and Asia-Pacific dominate consumption and build-out, supported by extensive shale extraction activities and surging municipal gas grid expansions managed by regional utilities and pipeline operators.
In-Depth Regional Review of Pipeline Developments
Regional analysis highlights North America as a mature yet expanding hub dominated by players like DCP Midstream Partners LP and Pembina Pipeline Corporation. Concurrently, the Asia-Pacific region demonstrates the fastest growth velocity, driven by rapid industrialization and aggressive municipal gasification initiatives across emerging economies.
Strategic Positioning of Leading Companies
Industry titans such as Tenaris Inc. and Nippon Steel Corporation secure their competitive edge through metallurgical innovation, supplying corrosion-resistant steel pipes. Meanwhile, EPC contractors like McDermott International Inc. and Mott Macdonald Group Ltd. capitalize on complex off-shore engineering and deepwater pipeline installation contracts.
Porter's Five Forces Analysis of the Sector
Porter's framework indicates moderate-to-high barriers to entry due to astronomical capital requirements and strict environmental permitting. Buyer power remains low for transmission-scale projects, whereas supplier power fluctuates based on raw steel availability from major mills like ChelPipe Group and Trubnaya Metallurgicheskaya Kompaniya Group.
SWOT Analysis of the Gas Pipeline Infrastructure Market
Strengths include established distribution networks and high reliability; weaknesses involve aging infrastructure vulnerability. Opportunities lie in digital twin integration and renewable natural gas (RNG) transport. Threats stem from aggressive regulatory decarbonization targets and substitution risks from electrified heating and renewable energy sources.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw steel and polymer synthesis by firms like MRC Global Corporation and National Oilwell Varco Inc. It flows through fabrication and coating by specialists like Europipe GmbH, engineering execution by Subsea 7 or Saipem SpA, and ultimately delivers gas to residential and commercial end-users.
Investment Insights and High-Potential Areas
High-potential investment avenues concentrate on integrity management technologies, automated valve retrofits (including advanced ball and gate valves), and compressor station optimization software. Investors should prioritize asset owners equipped for multi-product transport, including hydrogen and carbon capture infrastructure integration.
Conclusion and Key Takeaways for Market Stakeholders
In conclusion, the Gas Pipeline Infrastructure Market offers resilient long-term fundamentals anchored by a 5.36% CAGR through 2033. Stakeholders must prioritize technological modernization, regulatory compliance, and sustainable engineering practices to capture value in an evolving global energy matrix.
Research Methodology for Baseline Triangulation
Our baseline estimates are rigorously triangulated by synthesizing proprietary trade registry data, primary stakeholder interviews with C-suite executives at firms like TotalEnergies SE, Chevron Corporation, and British Petroleum plc, and secondary macroeconomic indicators sourced from international energy agencies.
Scope of the Report and Coverage Parameters
This report covers global deployment dynamics of transmission and distribution networks, evaluating equipment types from reciprocating compressors to gas flow metering skids. Limitations include unforeseen geopolitical embargoes and sudden shifts in national energy policies that could alter baseline macroeconomic forecasts.
Recent Developments and Strategic Industry Moves
Recent market activity is highlighted by strategic joint ventures, pipeline capacity expansions by Alliance Pipeline Ltd., and greenfield distribution network acquisitions by Redexis Gas SA and PT Pertamina Gas Negara Tbk, reflecting an industry-wide push to optimize cross-border supply chain resilience.